FIRST-TIME HOME BUYER INFORMATION HUBCall Richard: 416-899-8995

UNDERSTAND CONDO OWNERSHIP

Look beyond the
monthly condo fee.

What does the fee cover, and how well is the building prepared for future costs?

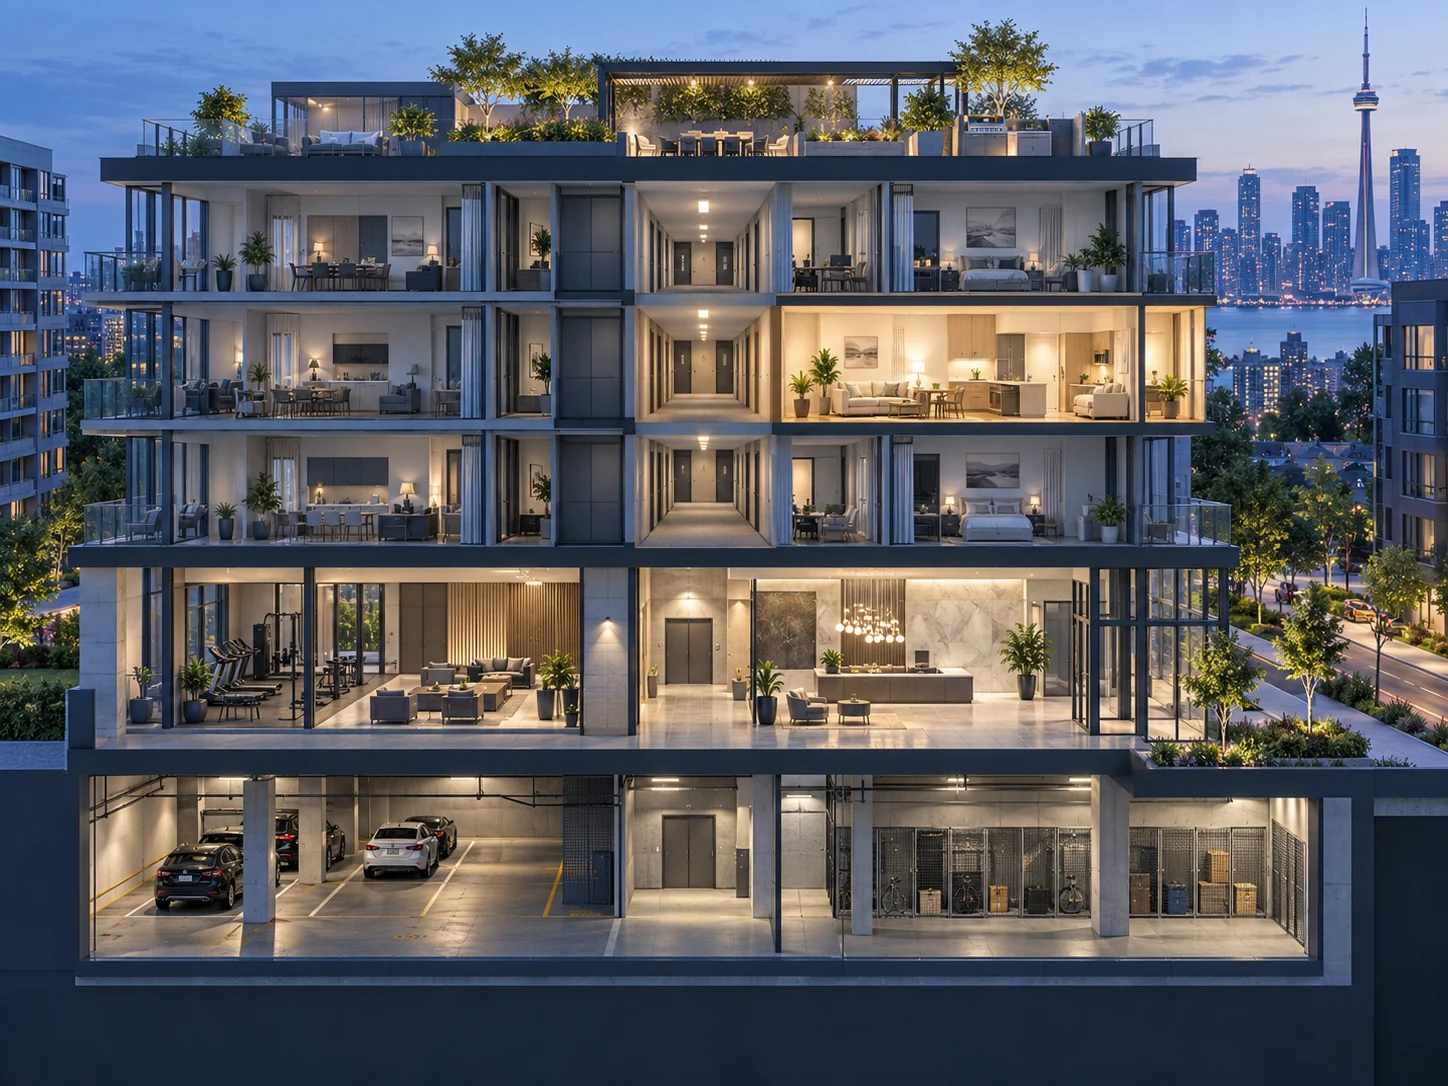
When you buy a condominium, you own your unit and an interest in shared property. A condominium corporation manages common elements under its governing documents. The details vary by building.

Illustrative condo building cutaway with one private unit highlighted among shared halls, lobby, roof space and parking

What you own

Your unit boundaries and rights to common elements depend on the declaration and plans. Parking and lockers may be owned units or exclusive-use common elements. Check the documents rather than assuming.

Illustration only; legal boundaries vary by condominium.
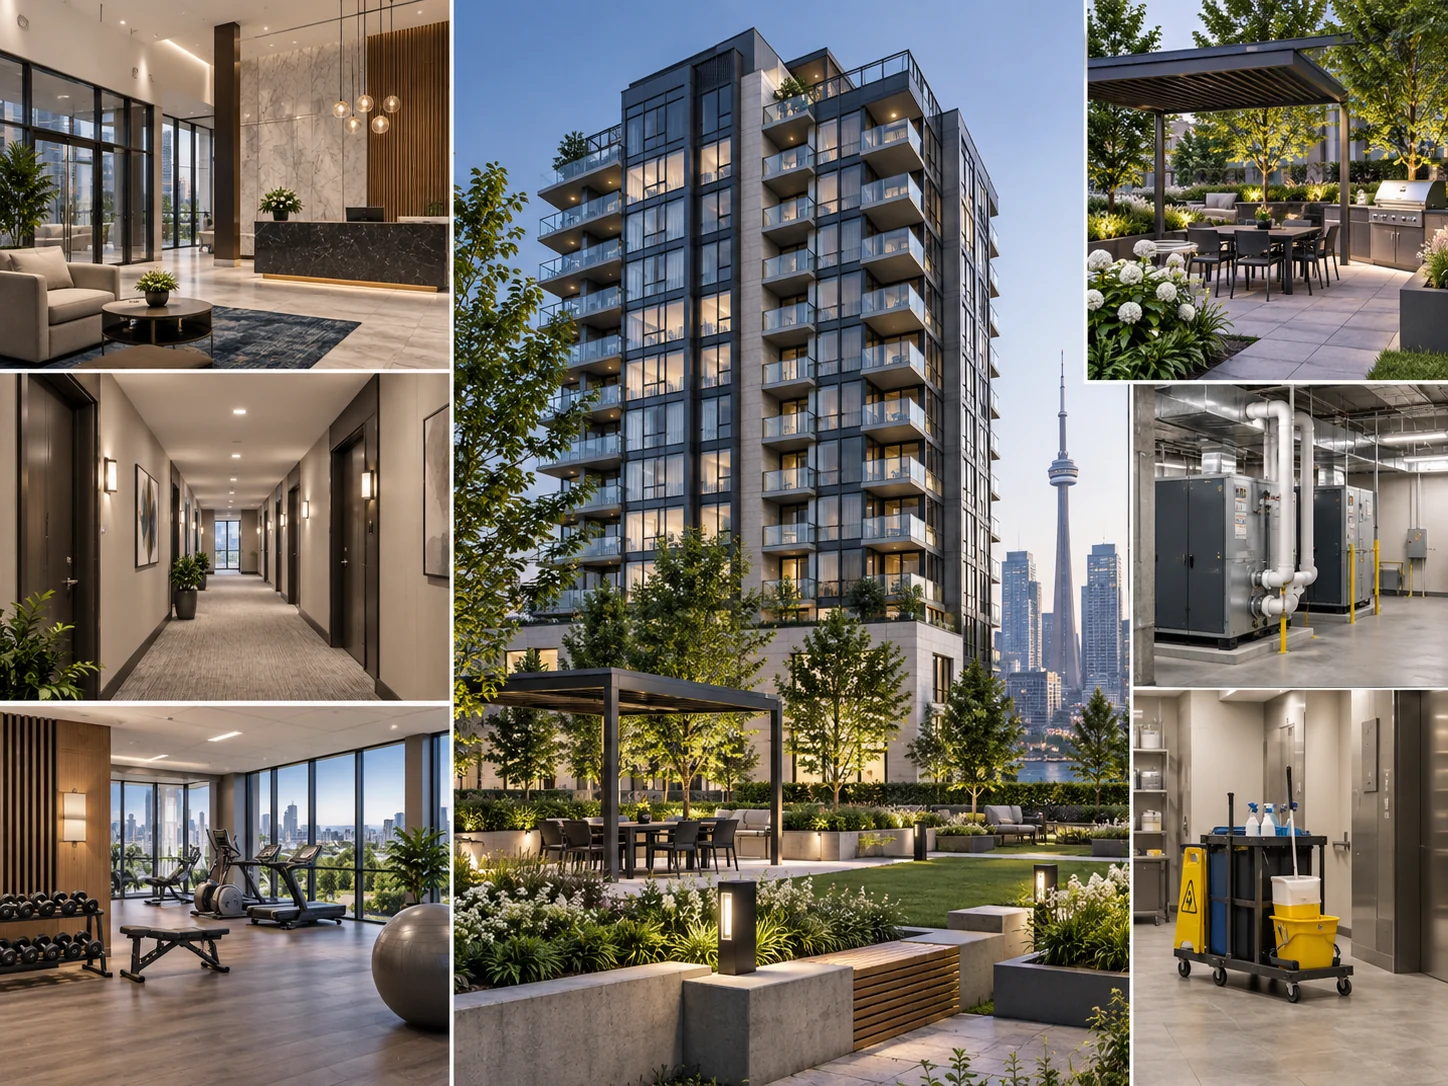
Illustrative condominium with shared lobby, halls, landscaping, amenities, maintenance equipment and cleaning supplies

What fees may cover

Fees can support common area upkeep, building insurance, services, amenities and reserve-fund contributions. Utilities and parking may or may not be included. Compare the actual inclusions.

Examples only; check the building budget and documents.

How to read the full cost

A monthly fee tells only part of the story. Compare these four things before deciding what a condo costs you.

01 · COMPARE UNIT SIZE

Fee per square foot

Divide the monthly condo fee by the unit’s square footage. This puts fees for differently sized units on a more comparable scale.

Example: $600 monthly fee ÷ 800 sq. ft. = $0.75 per sq. ft. each month

Use it as a comparison tool, then check what each fee includes.

02 · CHECK INCLUSIONS

Services and amenities

See which utilities, services, parking and amenities are included. Consider which ones you would actually use.

03 · LOOK AT THE BUILDING

Age and maintenance

Review the building’s age, maintenance history, reserve fund and planned major work.

04 · ADD YOUR COSTS

What you pay separately

Account for excluded utilities, your unit insurance and any repairs that remain your responsibility.

FOLLOW THE MONTHLY FEE

The fee is a starting point for questions.

What the corporation pays for, what you pay separately, and what may cost more later can differ from building to building.

YOUR MONTHLY CONDO FEEWhere does it go?
01 · OPERATIONS

Care of shared spaces

Common-area cleaning, building services, management and insurance may be funded through the fee.

02 · RESERVE

Planned major work

Contributions help fund future repairs and replacement of common elements.

03 · INCLUSIONS

Services and amenities

Utilities, parking, amenities and other inclusions vary. Read the actual budget and documents.

Also check what you pay separately

Unit insurance, excluded utilities and repairs inside your unit can still be your responsibility.

And what may change

Fees may rise, and special assessments can create an additional charge. Review the reserve fund and upcoming work.

Illustrative categories only. Your lawyer can review the specific building’s status certificate and supporting documents.

Don’t judge a condo by the headline monthly fee alone.

Ask: “What am I getting for that cost?”

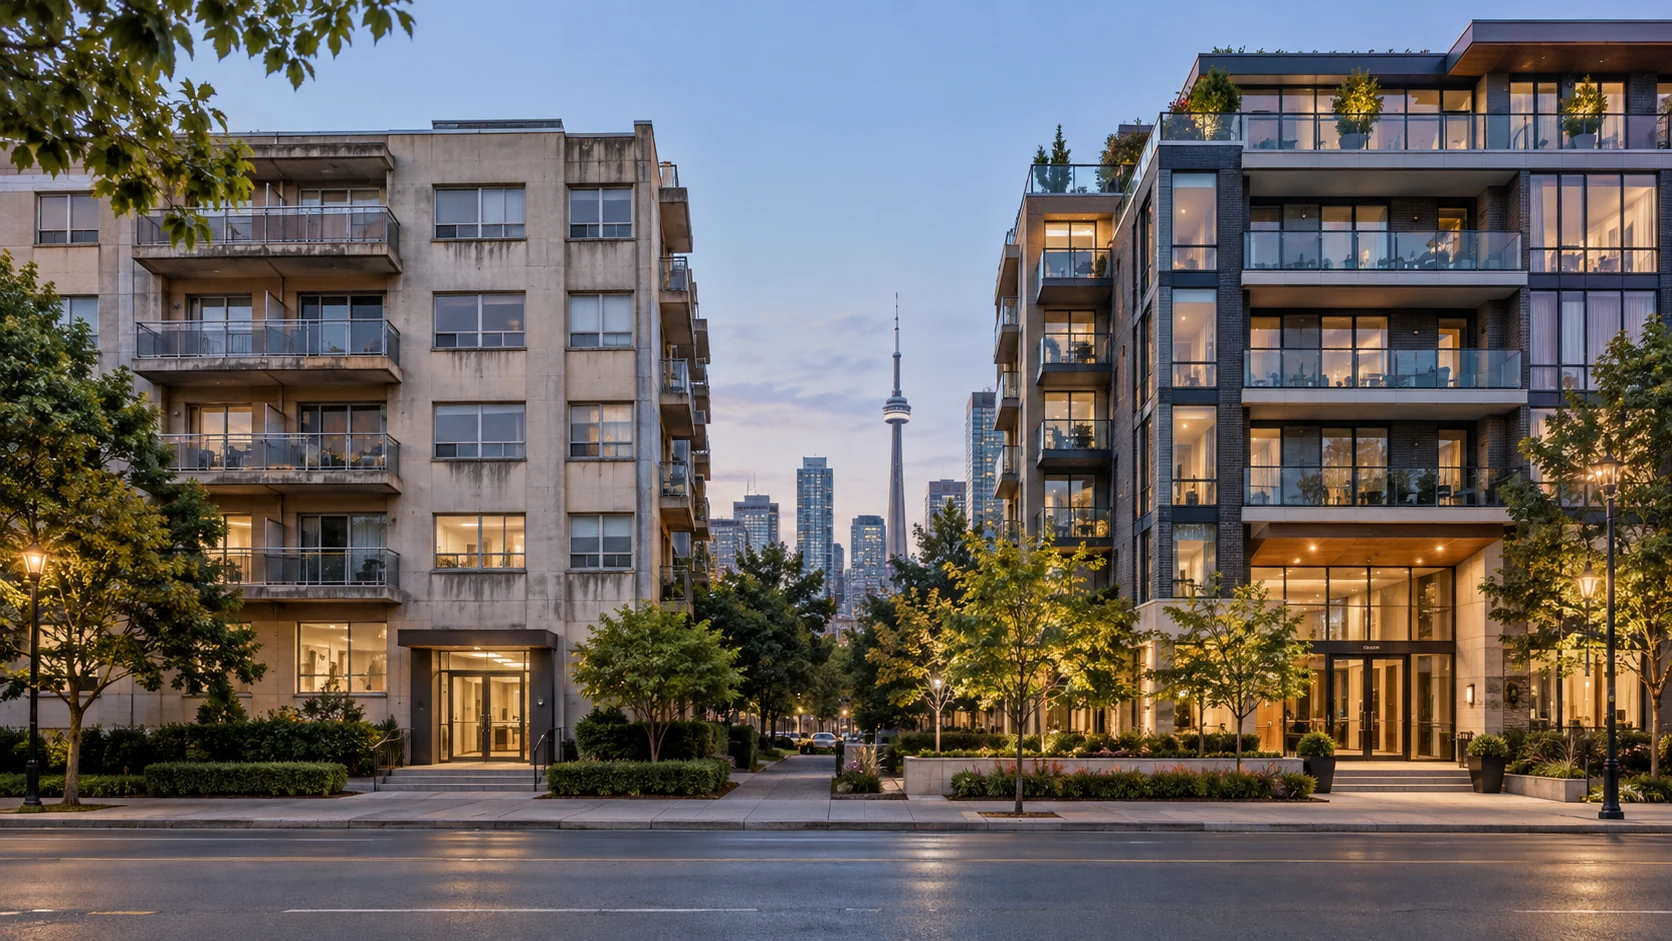
Building A vs. Building B

Two illustrative mid-rise condo buildings with different ages and shared features in a Toronto streetscape
Appearance and monthly fees alone cannot tell you which building is better managed. These are fictional examples, not current listings.

Building A

$450 per month

Questions to investigate:

  • Which utilities will you pay separately?
  • Which services or amenities are included?
  • What repairs are planned, and how will they be funded?

Building B

$620 per month

Questions to investigate:

  • Which utilities are included in the fee?
  • What services and amenities would you actually use?
  • What do the reserve fund and planned work reveal?

The lower fee is not automatically the better financial choice. Compare similar unit sizes, status certificates, budgets, reserve fund studies, insurance and your total monthly costs.

Documents and questions worth reviewing

Status certificate

  • Ask your lawyer to review the certificate and accompanying documents.
  • Look for litigation, arrears and anticipated fee changes.

Reserve fund

  • What major repairs are planned?
  • How will they be funded, and how do contributions compare with the reserve fund study?

Fee history and assessments

  • How have monthly fees changed?
  • Are one-time special assessments anticipated or recently charged?

Rules and lifestyle

  • Confirm pet, rental and renovation rules.
  • Check parking, lockers and amenity access that matter to you.

Common questions

Does a condo fee include every repair?

No. You may still pay for repairs inside your unit, insurance and items excluded from the corporation’s responsibilities. A special assessment can also create an additional cost.

Is a low condo fee always a good sign?

No. Check what the fee includes and whether the building has planned adequately for future work.

COMMON QUESTIONS

Questions first-time buyers often ask

What do condominium maintenance fees cover?

Direct answer: They may fund common-area operations, building insurance, management, amenities, utilities and reserve-fund contributions. Inclusions differ by corporation, so compare the actual budget and documents.

What is a status certificate?

Direct answer: It is a package of information about the condominium corporation and unit. A real-estate lawyer can review it for financial, legal and governance matters relevant to the purchase.

What is a reserve fund?

Direct answer: A reserve fund is money set aside by the condominium corporation for major repair and replacement of common elements. Buyers should consider its funding together with the reserve-fund study and planned work.

What is a special assessment?

Direct answer: A special assessment is an additional charge to owners for a specific funding need. The amount, timing and reason vary, so review the corporation’s records with your lawyer.

How should buyers compare condo fees?

Direct answer: Compare the fee per square foot, included services, building condition, reserve funding, fee history, planned work and costs you will pay separately. The lower headline fee is not automatically the better value.

Educational information reviewed September 24, 2026. Individual eligibility and lender requirements can vary.
VERIFY THE DETAILS

Official sources

Rules, limits and eligibility can change. Use these primary sources and confirm how they apply to your situation.

Links and program information reviewed September 24, 2026.